Merchant Services
Low-Cost Credit Card Processing for Small Business
Send us your last processing statement. We’ll show you what you’re actually paying per transaction, then quote transparent pricing, terminals and POS systems, including SALIDO POS.
The straight story on processing fees
Most business owners can’t say what they pay to accept cards. That’s no accident: statements are confusing, and a “low rate” on the sign-up sheet rarely matches what comes out of your deposits. The number that matters is your effective rate: total fees for the month divided by total card sales. If you don’t know yours, that’s where we start.
Every card transaction carries three layers of cost: interchange, set by Visa, Mastercard, Discover and Amex and paid to the card-issuing bank; card-brand assessments; and the processor’s markup. Nobody can lower the first two. What you can control is the markup, and how clearly it’s shown to you.
Pricing models compared
Interchange-plus
You pay true interchange plus a fixed, disclosed markup. The most transparent model, and usually the lowest cost for established businesses with steady volume.
Flat rate
One percentage on every sale. Simple and predictable for low-volume or new businesses, but you overpay on debit and other low-cost cards as volume grows.
Cash discount / dual pricing
Customers who pay with cash get a lower price, and card prices cover the fees. It can cut processing cost dramatically, but it must be set up to follow state law and card-brand rules.
Tiered (watch out)
“Qualified, mid-qualified, non-qualified” buckets. The low rate you were quoted only applies to some cards. Everything else gets bumped up. This is where most hidden cost lives.
What we set up
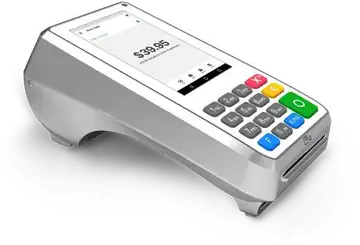
Countertop & wireless terminals
Chip, tap and mobile-wallet ready, for the front counter, the table or the job site.
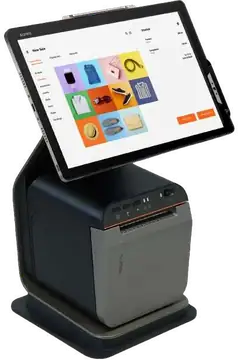
SALIDO POS
A full point-of-sale system with ordering, menus and inventory, paired with your processing account.
Online & invoice payments
Payment gateway, virtual terminal and payment links for e-commerce, phone orders and B2B invoices.
Fast deposits
Deposits as fast as the next business day are available on many accounts. We’ll tell you the deposit timing before you sign.
Questions to ask any processor before you sign
- Is there an early termination fee, and how much? Some contracts renew automatically for years.
- Is the terminal leased? A non-cancellable terminal lease can cost far more than buying the equipment outright.
- What are the monthly, PCI and statement fees? Small fixed fees add up when your volume is low.
- Is my pricing interchange-plus or tiered? Ask for it in writing.
- When do deposits hit my bank account? Cash flow matters as much as the rate.
Your card sales can also fund your growth
Businesses with steady card volume can qualify for working capital based on monthly sales, and new terminals or a full POS system can be leased instead of paid for in cash. One relationship covers both your processing and your financing.
Credit card processing FAQ
What is a good effective rate for credit card processing?
It depends on your industry, average ticket and card mix. Card-present businesses usually pay less than online or keyed-in sales. A statement review shows where you stand compared with what your volume should get.
Can I keep my current equipment?
Often, yes. Many terminals can be reprogrammed for a new account. If yours can’t, or it’s on a lease, we’ll tell you the real cost of switching before you decide.
Is cash discounting legal?
Offering a discount for cash is allowed. Surcharging credit cards has extra rules, and some states restrict it. We set programs up to follow state law and card-brand requirements.
Do I need good credit to get a merchant account?
Approval looks at your business type, processing history and risk, not just personal credit. New businesses and startups can be approved.
What do I need for a statement review?
Just one or two recent monthly processing statements. Email them to info@libertycapitalgroup.com or call 888-511-6223, and we’ll walk you through the numbers with no obligation.