Manufacturing Business Loans & Equipment Financing
Machines, materials and payroll funded the right way
Liberty Capital finances job shops, contract manufacturers, fabricators, food and beverage processors, plastics and packaging companies: CNC machines, presses, injection molders, packaging lines and the working capital to buy materials for big orders. New or used, nationwide.
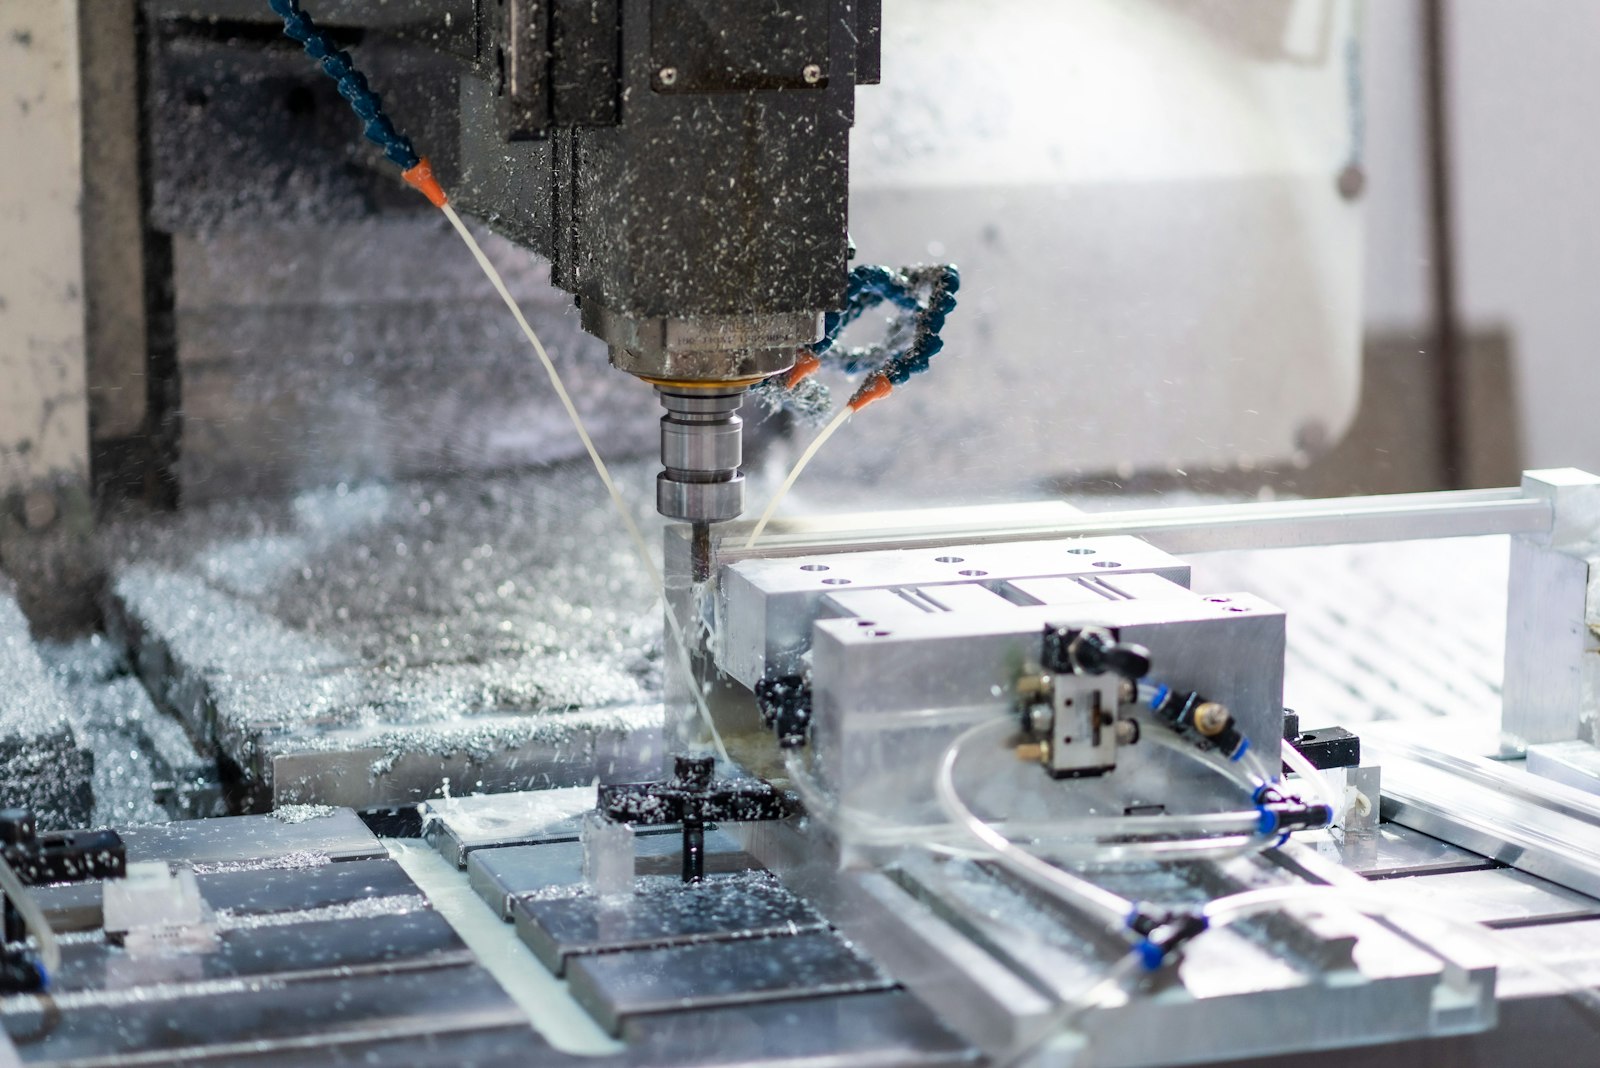
Manufacturing equipment we finance
Types of manufacturing business loans
| Option | Best for | Speed |
|---|---|---|
| Equipment financing & leasing | Machines and lines | 1–5 days |
| Equipment finance agreement (EFA) | Ownership from day one | 1–5 days |
| Business line of credit | Materials and payroll swings | 1–2 weeks |
| Working capital loan | A one-time need | 1–3 days |
| Term loan | Expansion and hiring | Days to 2 weeks |
| SBA loan | Real estate, acquisitions, long terms | 30–90 days |
| Invoice factoring | Slow-paying customers | 2–5 days |
| Inventory & PO financing | Funding a large order | 1–2 weeks |
| Sale-leaseback | Cash from paid-off machines | 1–3 weeks |
| Commercial real estate | Plant purchase or refinance | 30–60 days |
*Application-only limits vary by credit, time in business, equipment type and industry. Soft costs such as shipping, rigging, installation and tooling are program-dependent.
Leasing vs buying manufacturing equipment
Leasing is an inflation buster: a fixed payment while machine, steel and labor prices rise. It is cash flow management, a low capital outlay compared with buying outright, so cash stays free for materials and payroll on big orders. Payments are low and manageable, terms run up to 5 years, and most leases end with a $1 buyout.
Machines may qualify for Section 179, a potential 100% deduction in the year they go into service (ask your CPA). You conserve cash to take on more work, and the machine pays for itself while it runs.
What lenders look at
- $3K–$49,999: 600+ credit, application only
- $50K–$150K: 650+ credit, application only
- $150K and up: 650+ credit, 2–3+ years in business and financials
- Machine quote: year, make, model, condition
- Bank statements showing steady revenue
- $0 down is reserved for 5+ years in business, established PayNet and D&B business credit and 700+ personal credit
Three steps
- Short online application (soft inquiry)
- 3–4 months of business bank statements
- Equipment quote or invoice; multiple vendors on one payment
- Larger deals: tax returns and financials
Manufacturing business loan questions
What credit score do I need for a manufacturing business loan?
It depends on the program. Equipment financing can work with fair credit when you have a down payment and steady revenue, because the machine secures the deal. Unsecured working capital leans on revenue and time in business; SBA loans need the strongest credit and financials.
Can I finance used manufacturing equipment?
Yes. Used CNC machines, presses, injection molders and packaging lines are financeable. Newer used machines usually get longer terms.
How fast can a manufacturer get funded?
Application-only equipment financing and working capital can fund in 1–3 business days. Larger deals with full financials take 1–2 weeks; SBA loans take several weeks.
Can I include installation, shipping and tooling?
Usually, yes, depending on the program and approval.
How do I fund materials for a large order?
Purchase order financing, a line of credit or invoice factoring fits short-cycle needs better than a long-term loan.
Ready to add capacity?
Get a free quote or call (888) 511-6223.
Rates and terms disclosure: any rates, payments or terms shown are examples only. Sample rates apply to established businesses with 3 to 5+ years in business and strong credit (680+ FICO), subject to credit approval. Startup rates vary and are subject to final approval. Application-only limits vary by credit, time in business, equipment type and industry; amounts shown are guidance, not a promise. $0 down is reserved for businesses with 5+ years in business, established PayNet and D&B business credit and 700+ personal credit. This is not an offer or commitment to lend. Not tax advice; ask your CPA about Section 179.