Your Guide to Boom Truck Financing & Leasing
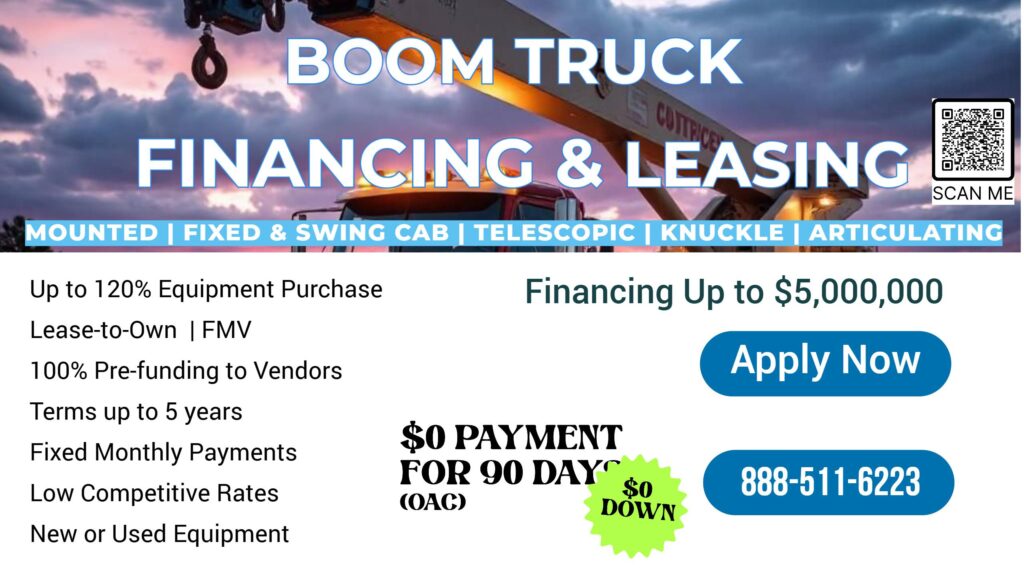
New or used. Dealer or private seller. Fixed, predictable monthly payments up to 60 months—often with $0 down for well-qualified borrowers. Get app-only approvals up to $250K; larger with financials.
Straight Talk: Why Leasing Wins for Depreciating Assets
Boom equipment depreciates. Don’t trap cash in a fixed asset. Leasing aligns cost with revenue, hedges inflation with fixed payments, and avoids the big down payments many banks demand on used units. Net: lower, predictable payments and more working capital for labor, fuel, and bids.
Compare Types of Financing for Boom Equipment
| Feature | Business Loans | Equipment Leasing | Equipment Financing (EFA) |
|---|---|---|---|
| Ownership | 50% | 100% | 100% |
| Initial Costs | $0 | Low–Moderate | Varies |
| Payments | Monthly / Daily / Weekly | Monthly | Monthly |
| Credit Minimum | ~500 | ~600 | ~650 |
| Disbursement | Client | Vendor | Vendor |
| New/Used Eligible | n/a | Yes | Yes |
| Maximum Term | 24 mo | 60 mo | 60 mo |
| Time in Business | 3+ yrs | Startup OK | Startup OK |
| Interest/Cost | Moderate | Low | Low |
| Application-Only Max | $150K | $250K | ~$250K |
Leasing is typically the most cost-effective for depreciating assets: lower entry cost, fixed predictable payments, and upgrade flexibility.
Loans & Capital Options Snapshot
| Type | Min FICO | TIB | Monthly Revenue | Amount | Starting Rates | Collateral |
|---|---|---|---|---|---|---|
| Factoring | 600+ | Any | $10k+ | $20k+ | 1–5% | Invoices |
| Term Loans | 550+ | 12+ mo | $20k+ | $1k–$3MM | 7%–18% | Unsecured |
| Equipment Loan | 600+ | Any | Startups OK | $20k–$5MM | 8%–36% | Equipment |
| Line of Credit | 650+ | 12+ mo | $20k+ | $100k+ | <10% | Unsecured |
| Commercial Loans | 650+ | Any | Any | $250k+ | 7%–18% | Property |
Boom Truck vs. Boom Lift Truck (Aerial Lift)
Boom Truck
- Utility: Hydraulic crane for heavy lifting; often with flatbed
- Industries: Construction, utilities, oil & gas, forestry
- Finance notes: Higher ticket; focus on maintenance history and resale
Boom Lift / Aerial
- Utility: Elevates crew/tools (articulating or telescopic)
- Industries: Telecom, utilities, building maintenance, tree care
- Finance notes: Generally lower ticket; great FMV lease candidate
Lift trucks/forklifts dominate warehousing, distribution, manufacturing, retail, and construction material handling.
Pros & Cons — From Both Sides
| Lease | Finance (EFA) | Pay Cash | |
|---|---|---|---|
| Working Capital | Preserved | Mostly preserved | Depleted upfront |
| Predictability | Fixed low payments | Fixed payments | None |
| Used Equipment | Easier than banks | Common | n/a |
| Upgrade Flex | FMV return/upgrade | Own day one | Buy again with cash |
| Lender View | Residual/condition risk | Collateral value risk | — |
Bottom line: For depreciating assets, leasing is typically the most cost-effective path: fixed, affordable payments and no large down payment.
Ask About Our Financing Promotions
- $99 for the first 6 months (kickoff with $99)
- 90-day Deferred Payments
- $0 Down or security deposit for well-qualified lessees
What You Get with Liberty Capital
- Fast, simple online app — no financials up to $250K (corp-only possible)
- 120% equipment cost (soft costs considered)
- Next-day funding approval possible
- 12–60 month fixed terms
- New or used; dealer or private seller
- Often does not report to personal credit
- FMV (off-balance-sheet), $1 buyout, and EFA
Boom Lifts & Aerial Lifts
- Lease-to-Own and FMV programs
- Great for frequent upgrades & safety tech
Lift Trucks / Forklifts
- Vendor financing friendly
- Seasonal payment plans available
Scissor Lifts
- Short-term rentals if temporary need
- Operational (FMV) leases for refresh cycles
Why It Matters (Owner’s View)
- Cash is king: Keep liquidity for payroll, fuel, permits, and growth
- Affordability: Fixed, predictable, low payments for up to 5 years
- Used friendly: Where banks say “no” or demand big collateral
- Private party OK: We verify and structure safely
Underwriter’s Lens
- Asset resale & condition history (depreciation is real)
- Bank balances/NSFs, time-in-business, and route/contract quality
- Structure: FMV vs $1 vs EFA; down payment or security deposit
Bad-credit paths may require collateral and/or larger deposits — still often cheaper than draining cash.
Boom Lift, Aerial Lift & Sign Truck Financing
The same programs cover the rest of the aerial family: articulating and telescopic boom lifts, bucket and sign trucks, scissor lifts and lift trucks. Ticket sizes are usually smaller than a boom crane, which makes them strong FMV lease candidates when you refresh equipment on a cycle, or $1 buyout / EFA when you plan to keep the unit.
- Articulating & telescopic boom lifts: new or used, dealer or private seller, 12–60 month terms.
- Sign and bucket trucks: see bucket truck financing and used bucket truck financing.
- Boom cranes and crane trucks: see crane truck financing.
- Other commercial trucks: start at the commercial truck financing hub.
What Do I Need to Apply?
- Online Application — submit and authorize (soft inquiry to start; hard pull at final equipment approval).
- Recent Bank Statements — typically last 3–4 months.
- Equipment Invoice/Quote — dealer or private seller; we can bundle soft costs.
- (If requested) Last year’s tax returns & current financials for larger tickets.
Join thousands who’ve financed with Liberty Capital over 20+ years. A dedicated funding manager will map options, timeline, and vendor payment.
Structures We Offer
- Off-balance-sheet FMV (incl. 10% FMV option)
- Capital Lease — $1 buyout
- Equipment Finance Agreement (own day one)
- Lease Rental Purchase Option (RPO)
Ready to compare FMV vs $1 vs EFA? We’ll model cash-flow and total cost side-by-side.
Boom Truck Financing FAQ
Can I finance a used boom truck?
Yes. We finance new or used boom trucks, boom lifts and lift trucks, from a dealer or a private seller. Age, hours and condition affect the structure, and a condition report may be required on older units.
Do you finance boom lifts and aerial lifts as well as boom trucks?
Yes. Articulating and telescopic boom lifts, scissor lifts, bucket and sign trucks and forklifts all qualify. They are typically lower-ticket than a boom crane, which makes them good FMV lease candidates.
What credit score do I need for boom truck financing?
As a guide, equipment leasing starts around a 600 score and an equipment finance agreement around 650. Challenged credit can still be approved, usually with additional collateral or a larger deposit.
How much down payment is required?
$0 down or a security deposit is available for well-qualified lessees. Lower credit files are usually structured with a down payment. Financing can cover up to 120% of the equipment cost, including soft costs.
How long can I finance a boom truck?
Terms run 12 to 60 months. Matching the term to the revenue the unit produces keeps the payment affordable and predictable.
How much can I get without submitting financials?
Application-only approvals go up to about $250,000. Larger amounts are available with financials, and corp-only structures are possible for qualified multi-owner entities.
Can I buy from a private seller?
Yes. Private-party purchases are considered; we verify ownership and structure the funding so both sides are protected.
What do I need to apply?
A one-page application, the last 3 to 4 months of bank statements and the equipment invoice or quote. We start with a soft inquiry; a hard pull happens at final equipment approval.