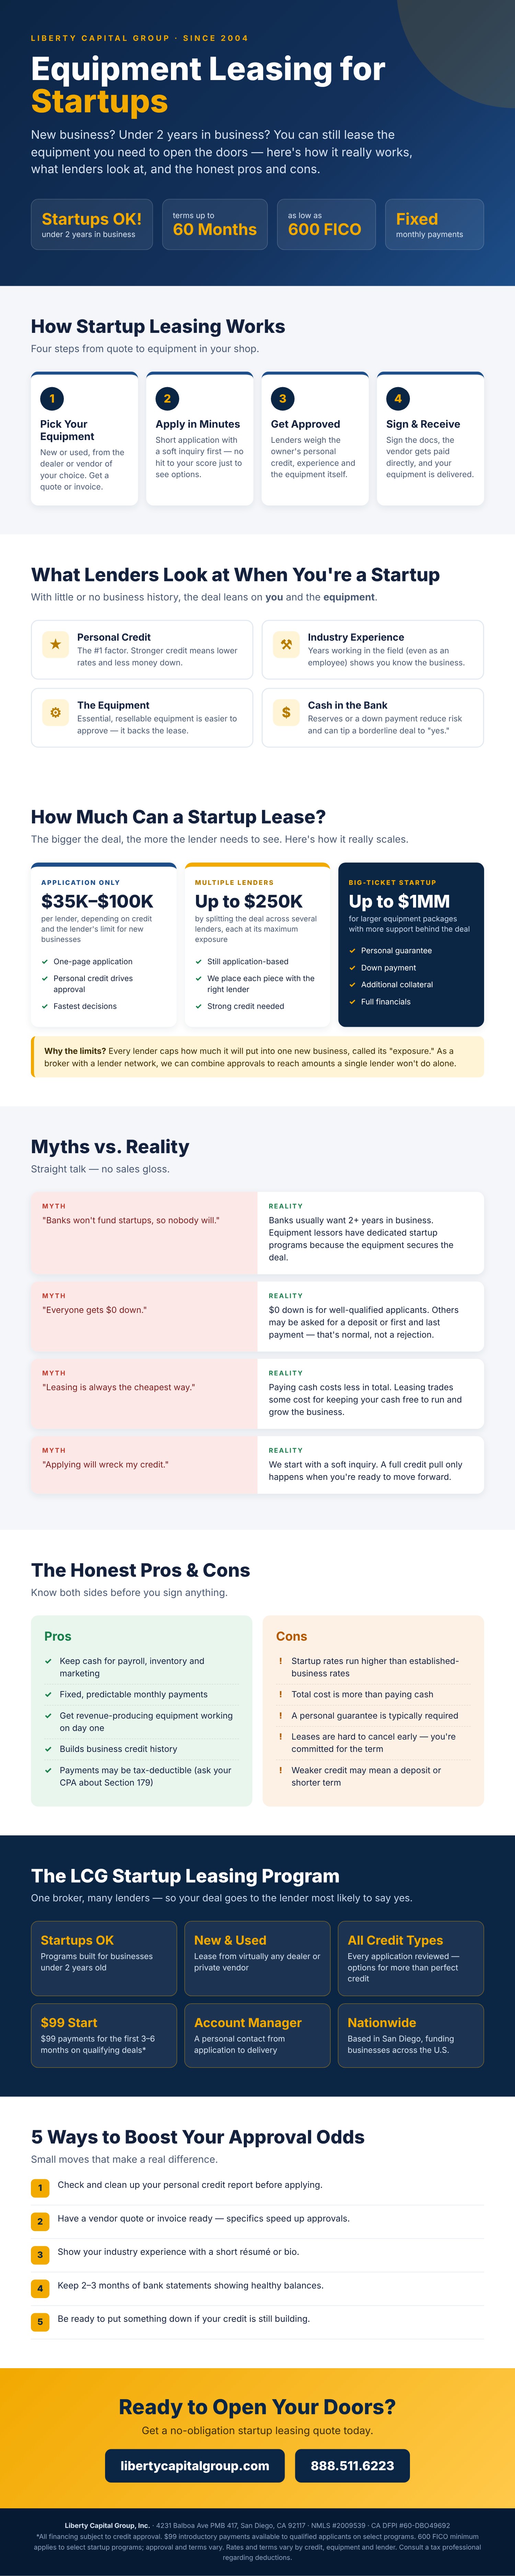
A new ultrasound system, imaging unit, dental chair, sterilization system, or lab analyzer can create revenue quickly, but the cash outlay can put real pressure on a practice. Knowing how to lease medical equipment gives you another way to acquire the tools your team needs without tying up every available dollar in one purchase.
For many healthcare operators, leasing is not simply a fallback when paying cash is impractical. It is a cash flow decision. The right lease can preserve working capital for payroll, supplies, marketing, facility costs, and the other expenses that keep patient care moving. The wrong structure, however, can leave you with a payment that outlasts the equipment’s useful life or terms that are more restrictive than expected.
Decide Whether Leasing Fits the Equipment and Your Plan
Medical equipment leasing works best when the asset will directly support operations, patient volume, or a new service line. A practice adding diagnostic capacity, replacing outdated technology, or expanding into a new treatment area may prefer predictable monthly payments over a large upfront purchase.
The equipment itself matters. Durable assets with a long usable life, such as exam tables, dental systems, imaging equipment, surgical tools, and laboratory equipment, are often strong leasing candidates. Technology that becomes obsolete quickly may call for a shorter term or a structure that allows the business to upgrade at the end of the agreement.
Before applying, ask a practical question: will this equipment generate or protect enough revenue to comfortably cover its payment? A new machine does not need to pay for itself on day one, but its expected contribution should fit your operating budget with room for normal fluctuations in patient volume and collections.
Lease versus equipment financing
A lease and an equipment loan can look similar because both create fixed payments. The difference is usually ownership and end-of-term flexibility. With equipment financing, you generally own the equipment after the loan is paid off. With a lease, the leasing company owns the asset during the term, and you may have options to purchase, return, renew, or upgrade it when the agreement ends.
A finance lease may be the better fit when you expect to keep the equipment for years and want a clear path to ownership. An operating-style lease can make more sense when upgrades are likely or preserving flexibility is the priority. The right choice depends on the equipment, expected useful life, tax treatment, and your long-term operating plan.
How to Lease Medical Equipment in Five Practical Steps
The fastest path to a workable offer starts before the application. Lenders and leasing companies can move more efficiently when the equipment, budget, and business profile are clearly defined.
1. Build a complete equipment quote
Request an itemized vendor quote that identifies the equipment, model numbers, installation, training, warranties, software, and any delivery costs. A vague quote can slow down underwriting or create a funding gap later if taxes, freight, or installation were not included in the financed amount.
If you are purchasing multiple items, determine which components are essential now and which can wait. Bundling the right equipment into one transaction can simplify payments. On the other hand, financing every add-on may increase the payment beyond what the new equipment revenue can support.
Equipment Dealers & VendorsOffer Financing On the SpotFree Vendor Package: program guide, credit guidelines & customer credit app. Close more sales, earn referral fees.Download Free →2. Set the payment target before reviewing terms
Do not begin with the maximum amount a lender may approve. Begin with the monthly payment that fits your cash flow. Review your average monthly revenue, existing debt payments, rent, payroll, supplies, insurance, and seasonality. Healthcare businesses with insurance reimbursement cycles should also account for the time between providing a service and receiving payment.
A longer lease term can lower the monthly payment, which may preserve cash in the near term. The trade-off is that total financing cost may be higher and the equipment may be less valuable by the time the term ends. A shorter term can reduce overall cost but requires more monthly cash. Neither is automatically better.
3. Prepare a clean application package
Requirements vary by transaction size, credit profile, time in business, and equipment type. Smaller transactions may require a short application and basic business information. Larger requests often call for bank statements, financial statements, tax returns, or a detailed explanation of how the equipment will be used.
Be ready to explain your business clearly: what services you provide, how long you have operated, why the equipment is needed, and how it will support revenue or efficiency. If a recent change affected revenue, provide context rather than leaving an underwriter to make assumptions.
4. Compare the full offer, not just the payment
A low payment can be appealing, but it is only one part of the agreement. Review the term length, amount due at signing, end-of-term option, early payoff language, documentation fees, insurance requirements, and whether the payment is fixed or variable.
Pay close attention to the purchase option. Some agreements allow a $1 buyout, meaning you can purchase the equipment for a nominal amount at the end. Others may include a fair market value purchase option, where the end price depends on the asset’s value at that time. A third structure may require a fixed percentage buyout. These details affect both the economics and your flexibility.
5. Match the structure to your growth timeline
A practice opening a new service line may need a modest payment during the first few months while referrals and patient demand build. An established facility replacing equipment with a proven revenue history may be positioned for a shorter, more aggressive term.
This is where working with a financing advisor can help. Rather than forcing every borrower into one program, Liberty Capital Group can compare available leasing structures and help identify terms that make sense for the equipment, revenue pattern, and ownership goal.
Understand What Drives Approval and Pricing
Leasing companies generally evaluate the strength of the business, the value and resale potential of the equipment, the requested amount, and the credit profile of the applicant. Established revenue, healthy bank activity, a reasonable debt load, and a clearly defined equipment purchase can improve available options.
Credit matters, but it is not the only factor. A business with less-than-perfect credit may still qualify for equipment leasing, particularly when the equipment has solid collateral value and the business can document stable revenue. The available terms may differ, so it is especially important to compare offers carefully instead of accepting the first approval.
Some lenders may require a personal guarantee, a down payment, or additional documentation. These are not automatically deal breakers, but they should be understood before signing. Ask what happens if you pay off early, sell the business, need to relocate, or want to add equipment before the current lease ends.
Protect Cash Flow After the Lease Closes
The lease payment is not the only ongoing cost of the equipment. Include maintenance contracts, calibration, software subscriptions, consumables, insurance, staff training, and potential downtime in your financial planning. Equipment that appears affordable based on the lease payment alone can become expensive if operating costs were overlooked.
It is also wise to keep a cash reserve after funding. Leasing can preserve working capital, but it should not be used as a reason to ignore the broader balance sheet. A practice still needs liquidity for unexpected repairs, delayed reimbursements, staffing needs, and growth opportunities.
Tax treatment may be another consideration. Depending on the structure, equipment and lease payments may be treated differently for tax purposes. Your CPA or tax advisor should review the agreement before closing so the financing decision supports your broader tax strategy rather than creating an avoidable surprise.
Questions to Ask Before You Sign
Before committing, get direct answers to these points:
- What is the total amount due at signing and the exact monthly payment?
- What are my options at the end of the lease term?
- Can I pay off the lease early, and what would that cost?
- Are there documentation, processing, renewal, or return fees?
- Who is responsible for maintenance, insurance, installation, and equipment removal?
The best lease is not necessarily the one with the lowest advertised payment. It is the one that gives your business the equipment it needs, leaves room for day-to-day operations, and provides an end-of-term outcome you can live with.
Request a payment quote before you commit to a vendor contract, then compare the terms against your expected cash flow. The right medical equipment lease should help your practice serve more patients and operate with confidence, not create the next cash flow problem.