A walk-in cooler fails on a Friday afternoon. A supplier wants payment before the next delivery. A second location becomes available, but the build-out deposit is due before the opportunity disappears. These are not theoretical problems for restaurant operators, and they rarely arrive when cash flow is at its strongest. Can restaurants get business financing? Yes – and the right structure depends on what the capital needs to accomplish, how the restaurant earns revenue, and how quickly funds are needed.
Restaurants can be financeable even when a traditional bank sees a seasonal revenue pattern, thin margins, or a short operating history as a reason to hesitate. The key is matching the financing to the use of funds rather than forcing every need into one conventional term loan.
Can Restaurants Get Business Financing for Real Operating Needs?
Restaurant financing is available for working capital, equipment purchases, renovations, inventory, expansion, debt refinancing, and unexpected repairs. Approval is never automatic. Lenders commonly review time in business, monthly deposits, card sales, average bank balances, existing obligations, credit profile, and the purpose of the request.
That said, restaurant owners should not assume that a bank decline is the final answer. Banks tend to prefer clean financial statements, strong collateral, stable cash flow, and a slower underwriting process. Alternative financing programs can look more closely at revenue trends, equipment value, or the strength of the business’s daily deposits. That creates more options, but it also makes careful offer comparison essential.
A practical financing decision starts with one question: will this capital produce or protect enough cash flow to support the payment? Replacing a failing oven that keeps the kitchen running is different from financing a cosmetic update with no clear return. Both may be valid uses of capital, but they call for different payment terms and risk tolerance.
Match the Funding Type to the Restaurant Need
Working capital for inventory, payroll, and timing gaps
Working capital is designed for the ongoing costs that keep service moving: food and beverage inventory, payroll, rent, marketing, repairs, and supplier obligations. A business line of credit can be useful when the need repeats. The restaurant draws only what it needs, repays the balance, and may draw again if the facility remains available.
For a one-time cash need, an unsecured business loan may offer a set funding amount and predictable payment schedule. It can make sense for a planned marketing campaign, a short renovation, a catering contract that requires up-front purchasing, or a seasonal inventory build.
The payment must fit the restaurant’s slower weeks, not just its strongest month. Operators should review the full cash flow cycle: when deposits arrive, when vendors draft payments, when payroll hits, and how much cushion remains after fixed expenses. Fast capital can solve a timing problem, but an aggressive payment can create the next one.
Equipment financing for revenue-producing assets
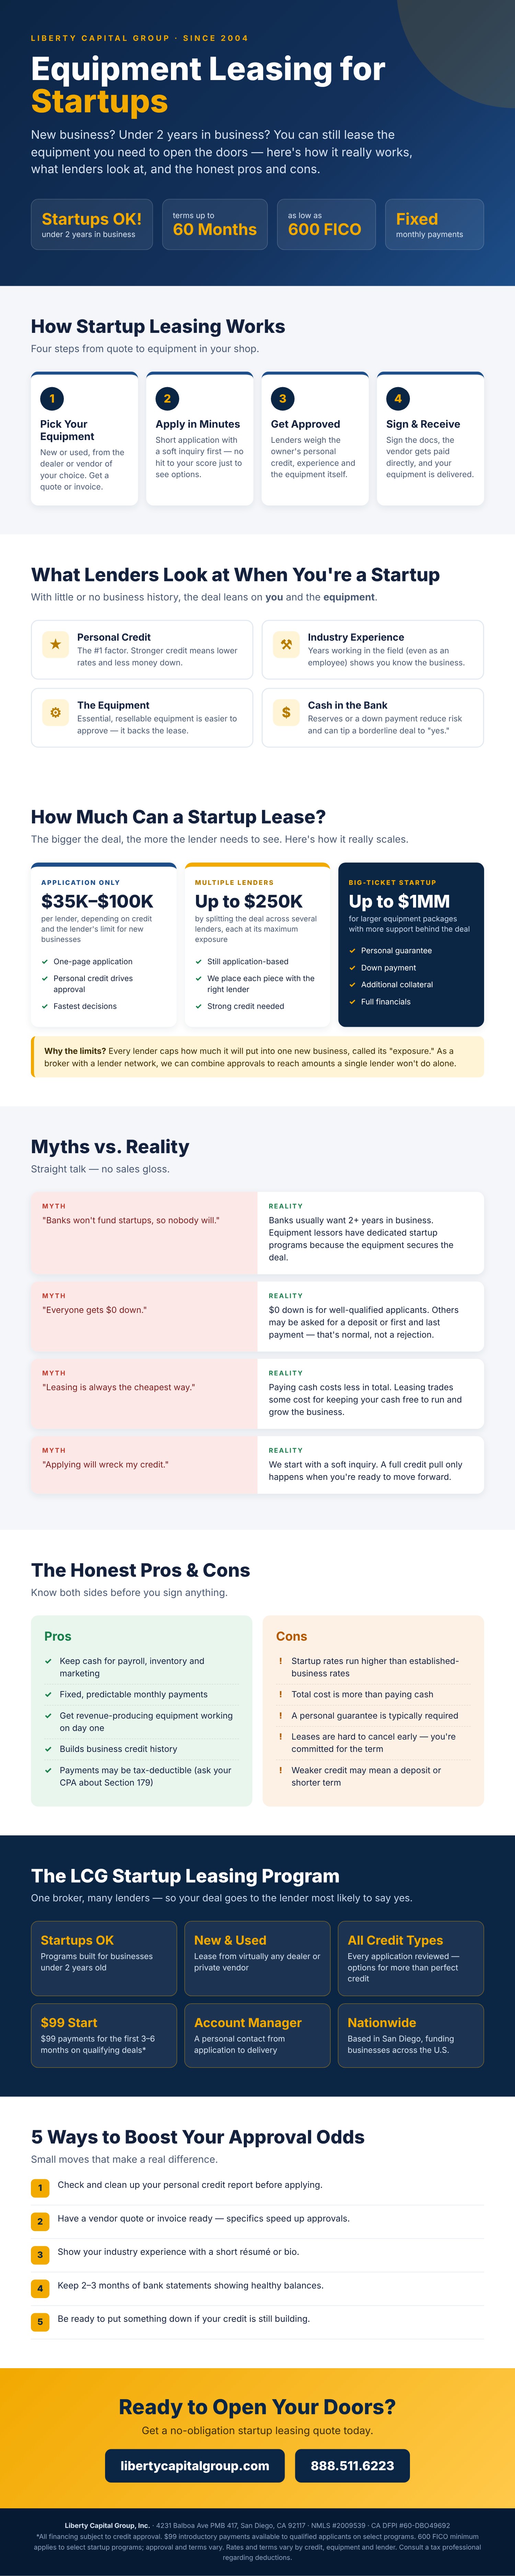
Commercial kitchen equipment is often one of the cleanest uses of financing because the asset itself has value. Refrigeration, ovens, ranges, dishwashers, prep equipment, point-of-sale systems, furniture, and ventilation systems may qualify for equipment financing or leasing.
Equipment financing generally works well when the restaurant wants to own the asset over time. Equipment leasing may be a better fit when preserving cash is the priority, when technology becomes outdated quickly, or when the business wants a structured end-of-term option. The equipment commonly serves as collateral, which can make financing more accessible than an unsecured request.
Equipment Dealers & VendorsOffer Financing On the SpotFree Vendor Package: program guide, credit guidelines & customer credit app. Close more sales, earn referral fees.Download Free →The best structure is not always the lowest advertised rate. Consider the down payment, monthly payment, term length, ownership option, maintenance responsibilities, tax treatment, and whether the equipment will still be useful after the agreement ends. A lower monthly payment can help cash flow, but extending the term may increase total cost.
Merchant cash advances for urgent, short-term needs
A merchant cash advance can provide capital based largely on future card sales or business deposits. For restaurants with steady transaction volume and a genuinely urgent need, it may deliver funds faster than more traditional financing.
Speed comes with a trade-off. The cost can be higher than other forms of capital, and frequent remittances can pressure operating cash flow. This option deserves a clear repayment plan. It is generally better suited to a short-term opportunity or emergency with a defined payoff path than to routine operating losses that continue month after month.
Financing for renovations and expansion
An expansion can increase sales, but it can also consume capital long before the first additional table is served. Construction deposits, permits, furniture, signage, equipment, opening inventory, and staff training all require cash. Restaurant owners should avoid treating the project budget as the entire capital need.
Build a contingency into the plan. Delays, change orders, permit issues, and slower-than-expected ramp-up are common. Financing may be structured through a combination of working capital, equipment funding, and a term loan rather than one large request. Separating the uses of funds can align short-lived expenses with shorter repayment periods and long-lived assets with longer terms.
What Lenders Want to See
A strong application tells a clear business story. The numbers should show how the restaurant generates revenue, where cash flow is going, and why the requested capital improves the operation. Inconsistent deposits are not necessarily disqualifying, but unexplained declines, overdrafts, and stacked payment obligations will raise questions.
Have recent business bank statements ready, along with processing statements if card sales are a meaningful share of revenue. Lenders may also request a profit and loss statement, balance sheet, debt schedule, government-issued identification, business formation documents, equipment quote, lease agreement, or a brief explanation of the project.
Accuracy matters. Do not inflate revenue, minimize existing obligations, or apply for more than the business can reasonably support. A well-prepared request gives a funding advisor more room to identify programs that fit the restaurant instead of chasing an approval that creates an unmanageable payment.
Improve Your Financing Position Before Applying
Restaurant owners do not need perfect financials to pursue financing, but a few steps can strengthen the file. Keep business and personal expenses separate, reconcile bank accounts regularly, document revenue changes, and avoid unnecessary overdrafts. If an existing obligation is draining cash flow, refinancing or consolidating it may be worth evaluating before adding new debt.
It also helps to be precise about the request. “We need money” is difficult to underwrite. “We need $65,000 to replace refrigeration, purchase a second prep line, and cover installation, which should reduce product loss and increase catering capacity” gives lenders a usable picture of the opportunity.
Timing matters as well. Applying before equipment fails or before a landlord deadline is imminent gives you more choice. When an operator has days rather than weeks to act, speed may become the deciding factor, and the available terms may be less favorable.
Compare Offers Like an Owner, Not Just a Borrower
Approval is only the beginning. Review the payment amount, payment frequency, total repayment, collateral requirements, prepayment terms, personal guarantee, funding timeline, and any fees deducted from proceeds. A daily or weekly payment may be manageable for a high-volume quick-service operation but difficult for a restaurant with uneven weekly sales.
Look beyond the stated rate. Two offers with the same funded amount can have very different cash flow effects. Ask how much will actually reach your account after fees, when the first payment is due, and what happens if revenue falls temporarily. The right financing should support operations while leaving room to buy inventory, pay staff, and handle ordinary surprises.
Liberty Capital Group helps restaurant owners evaluate multiple funding paths and match the payment structure to the business need. Whether the priority is a kitchen equipment upgrade, cash flow support, or an expansion opportunity, a clear review of the numbers can prevent a fast decision from becoming an expensive one.
If a restaurant opportunity or operating need is in front of you, request a payment quote and compare realistic financing options before the pressure becomes an emergency.