MRI Equipment Financing: A Plain-English Guide
An MRI is one of the biggest purchases an imaging practice will ever make. Paying cash for it drains the reserves you need for staff, payroll and marketing. Financing spreads the cost over the years the scanner is earning money. Liberty Capital Group has arranged equipment financing since 2004. We finance $10,000 up to $5,000,000, and we tell you up front what will and won’t get approved.
What Does an MRI Cost?
Prices vary widely by field strength, age, vendor and condition. As a rough guide:
- New 1.5T systems: can range from about $1 million to $1.5 million or more.
- New 3T systems: can range from about $1.5 million to $3 million or more.
- Refurbished 1.5T systems: can range from roughly $300,000 to $800,000.
- Refurbished 3T systems: can range from roughly $700,000 to $1.5 million.
- Open, extremity and compact systems: can range from roughly $150,000 to $700,000, new or used.
The scanner is only part of the bill. RF shielding, magnetic shielding, HVAC and electrical upgrades, rigging, installation and staff training can add $100,000 to $500,000 or more depending on the site. Get a full quote from your vendor before you apply so nothing surprises you later.
Who Finances MRI Equipment?
We work with outpatient imaging centers, hospitals, orthopedic and sports medicine groups, neurology practices, mobile MRI operators and veterinary imaging centers.
- Corporate-Only Approvals Are Available
Some lenders will approve a deal on the strength of the business alone, with no personal guarantee. This is built for corporations with a strong financial history and multiple owners. Most hospitals and larger groups qualify. Sole owners and startups can still apply, but corporate-only amounts will be limited or unavailable.
- Up to 120% Financing
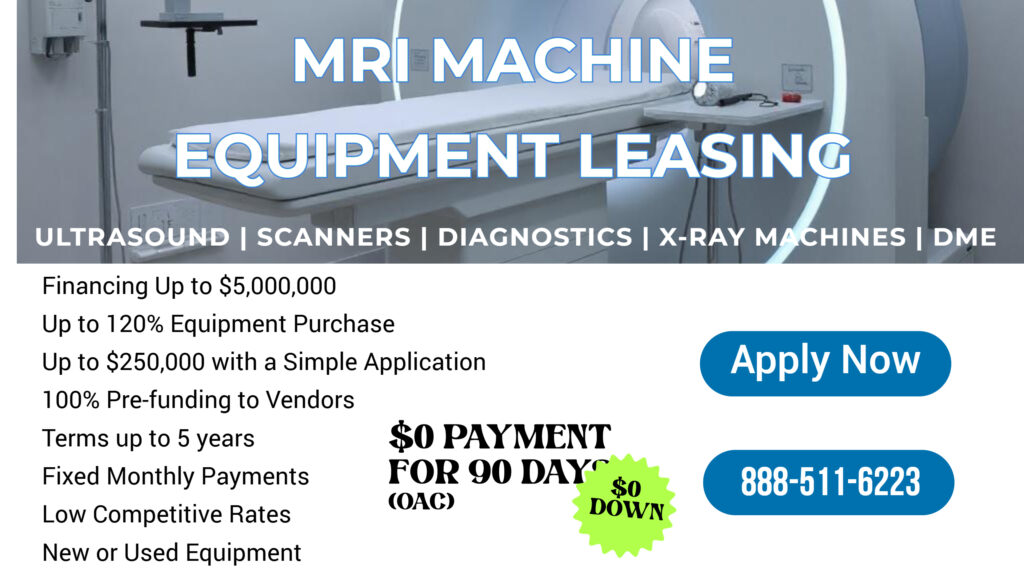
We can finance up to 120% of the equipment cost, subject to approval. For MRI, that can include soft costs like RF shielding, site build-out, rigging, delivery, tax, installation and training. That keeps your cash in the bank instead of in the walls of the scan room.
- Flexible Funding Amounts
We finance $10,000 up to $5,000,000. Application-only approvals commonly go up to $250,000. That limit depends on your credit, time in business, the equipment and your industry. Treat it as guidance, not a promise. Larger MRI deals need financials.
- The Right Approval Beats the Fastest One
Smaller deals can be approved quickly. But speed is not the point. The point is the right approval at the right rate and term. You want someone screening your file and shopping it to the lenders most likely to say yes on good terms. That is our job.
- Approved MRI Vendors
We work with manufacturers, dealers and new and used equipment resellers nationwide. Buying from a private seller is possible, but expect more scrutiny. The seller must prove ownership and a clear title.
- A, B and C Credit Determine the Rate
Your credit tier sets your rate. We don’t publish rates because they depend on your full file. Our goal is to get you an approval. Your job is to accept it or walk away. No harm done.
- New and Used MRI Equipment
New and refurbished systems both qualify. Used equipment often carries a shorter term, and the lender may want an inspection or appraisal on older units.
- Business Credit, Not Personal Debt
Most MRI financing reports to business credit and is secured by a UCC filing on the equipment. It generally does not show up as personal debt. Most deals still require a personal guarantee, so you are personally on the hook if the business can’t pay.
- Early Payoff: How It Really Works
Equipment financing agreements are commercial and non-cancellable. You can pay early, but the payoff is generally the sum of the remaining payments. Don’t assume early payoff saves interest. Ask before you sign.
MRI Financing vs. Business Loans and MCA
Feature | Business Loans | Merchant Cash Advance | Equipment Financing |
Ownership | 50% | 50% | 100% |
Origination, Admin Titling Fees | Low | Low to moderate | Varies |
Monthly Payments | Monthly, Daily, Weekly | Daily / Weekly | Monthly |
Credit Minimum | 600 | 500 | 600+ |
Fund Disbursements | Client | Client | Vendor |
New/Used Equipment | n/a | n/a | Yes |
Maximum Term | 24 months | 12 months | 60 months |
Time in Business | 2+ years | 6 months | 1+ year (startups case-by-case) |
Interest Rates | Moderate | High | Low |
Application Only | $150K | $250K | $250K* |
Funding Time | Same day | Same day | 1–5 days |
*Application-only limits are guidance, not a promise. They vary by credit, time in business, equipment type and industry. All programs subject to credit approval.
MRI Equipment Financing Credit Requirements
$10,000 to $150,000
- Credit score of 600 or higher
- 1+ year in business
- Personal guarantee (FICO 600+)
- Recent business bank statements
- Startups considered case by case with a down payment or additional collateral
$150,000 to $250,000+
- Credit score of 650 or higher
- 2+ years in business
- Personal guarantee (FICO 650+)
- 2 years of business and personal tax returns
- Personal financial statement
- Interim profit and loss statement and balance sheet
- Bank reference
Most full-size MRI systems fall in the second tier. Have your financials ready and the process moves faster.
MRI Financing and Leasing Programs
Equipment Financing
An equipment finance agreement (EFA) works like a loan. You make fixed monthly payments and own the MRI at the end of the term.
Equipment Leasing
A lease gives you two paths. A fair market value (FMV) lease keeps payments lower and lets you return, renew or buy the system at the end. That suits practices that plan to upgrade technology. A $1 buyout lease is lease-to-own. Most of our leases are $1 buyout.
Why Lease an MRI?
- Beat inflation: lock in today’s price and payment before equipment costs rise again.
- Manage cash flow: a lease takes far less capital up front than an outright purchase.
- Low, manageable payments: fixed payments you can plan around.
- Terms up to 5 years: most with a $1 buyout.
- Tax benefits: you may qualify for Section 179 and a potential 100% first-year deduction. Consult your tax advisor.
- Conserve cash: keep your reserves for payroll, marketing and the unexpected.
Current Specials (OAC)
- $99 per month for the first 6 months
- 90-day deferred payments
- $0 down
- 0% security deposit
- No additional collateral for qualified borrowers
- Terms up to 60 months
All specials are on approved credit. Lower credit may still be approved with a down payment, security deposit or collateral. Startups can be financed through SBA programs or startup equipment financing with a down payment or collateral.
Get a soft-pull quote or call 888-511-6223.
Why MRI Financing Is Easier Than a Bank Loan
Equipment financing is easier to qualify for than a traditional bank loan. Here’s why:
Less paperwork
Faster approvals
Easier qualifying requirements
The equipment serves as primary collateral
Credit flexibility with down payment or collateral
Skip the Bank Hopping: How a Broker Speeds Up MRI Financing
Going bank to bank for an MRI loan eats weeks. Each bank pulls your credit, asks for the same documents and may still say no. Most banks also don’t understand imaging equipment.
Liberty Capital Group is a broker that works like a banker. We have multiple lenders under one roof. We know which ones like MRI deals, which take used equipment and which will work with lower credit. We structure the deal to fit your profile and send it to the right lender the first time. That saves you time and money.
What Do I Need to Apply?
- 1. Online application. We do a soft pull to quote you, so there’s no hard inquiry to see your options. The lender does a hard pull once you move forward. Apply here.
- 2. Equipment invoice or quote. Buying from more than one vendor, such as the scanner, shielding and injector? We can combine them into one monthly payment.
- 3. Bank statements (3 to 4 months). These show income, funds for a down payment if needed, and the account for ACH autopay.
Larger deals also need the financials listed in the credit requirements above.
Equipment Financing Built for Healthcare
Imaging technology changes fast, and patients expect current equipment. Financing lets you add or upgrade an MRI without tying up the cash your practice runs on. The scanner can start generating revenue while you pay for it.
Why MRI Deals Need an Experienced Broker
MRI transactions are large and complex. A real underwriter reviews every file, verifies the vendor and the equipment to prevent fraud, and coordinates payment with the vendor, often in stages tied to delivery and installation. A business loans broker who has done these deals keeps the process on track and steers you away from bad terms. Call 888-511-6223 to talk it through.
MRI Equipment Financing FAQs
Can I finance a used or refurbished MRI?
Yes. Refurbished MRI systems are commonly financed. Terms may be shorter on older units, and the lender may require an inspection or appraisal. Private-party sales are possible if the seller can prove ownership.
Can soft costs like RF shielding be financed?
Often, yes. With up to 120% financing, subject to approval, the deal can include RF shielding, site build-out, rigging, delivery, tax, installation and training.
What credit score do I need?
For $10,000 to $150,000, plan on 600+ credit and 1+ year in business. For $150,000 to $250,000 and up, plan on 650+ credit, 2+ years in business and full financials. Lower credit may be approved with a down payment, security deposit or collateral.
Can a startup imaging center get MRI financing?
Yes, case by case. Startups usually need a down payment or additional collateral. SBA loans and startup equipment financing are also options.
Should I lease or finance an MRI?
If you want to own the scanner, use an equipment finance agreement or a $1 buyout lease. If you plan to upgrade in a few years, an FMV lease keeps payments lower. Terms run up to 60 months either way. You may qualify for Section 179; consult your tax advisor.
Can I pay off my MRI financing early?
Yes, but the agreement is commercial and non-cancellable. The payoff is generally the remaining payments, so paying early usually doesn’t save much interest.
Will MRI financing show on my personal credit?
Most MRI financing reports to business credit and is secured by a UCC filing, not reported as personal debt. A personal guarantee is typically required, and the lender does a hard pull when you move forward.
How fast can I get approved, and how is the vendor paid?
Smaller application-only deals can be approved quickly. Larger MRI deals take longer because an underwriter reviews financials. Once documents are signed, the lender pays the vendor directly, sometimes in stages tied to delivery and installation.
Our small business financing experts are available to guide you through the funding Process.
Instant Quote Online
Use our instant online quote calculator to get an accurate no obligation quote.
Apply Online
Complete our quick online application. Application takes 5 mins.
Review Your Options
We will contact you to review your options.
Get Funds
Money will be deposited in your account in as little as 24 hours.