See which business financing you're likely to qualify for
Lenders look at dozens of things, but three numbers drive most decisions: monthly revenue, time in business and personal credit. Tap your answers below and the indicator shows which programs fit, how strong the fit is, and what usually gets approved on the application alone.
Your results
Choose your answers above.
Indicative only, based on typical lender guidelines. Not an offer or commitment to lend. Industry, cash flow, existing debt and other factors also count. All financing subject to credit approval.
What lenders look for in each number
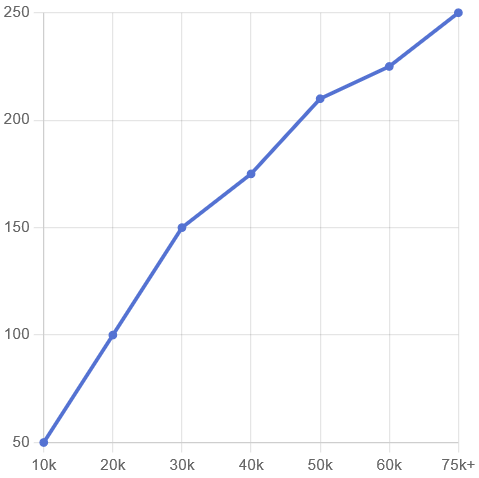
Revenue shows you can make the payment. Lenders read your last 3 to 4 months of bank statements, not just your tax return.
- $10K+ a month opens revenue-based working capital
- $20K+ a month for most non-bank term loans
- $50K+ a month and strong balances for bank-style loans
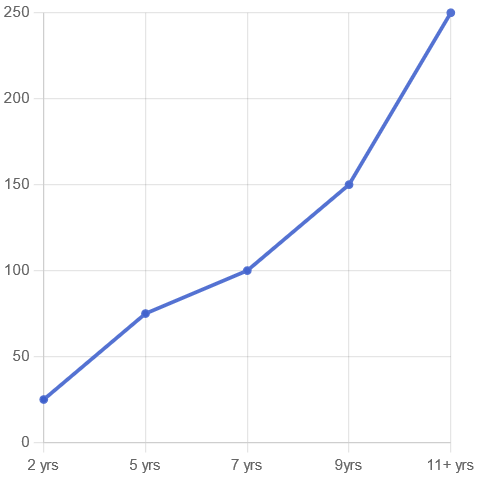
Every year of history lowers the risk a lender sees, and raises what you can get without financial statements.
- Startups: equipment financing with a down payment
- 6+ months: working capital programs
- 12+ months: non-bank term loans
- 2+ years: bank loans and bigger application-only limits
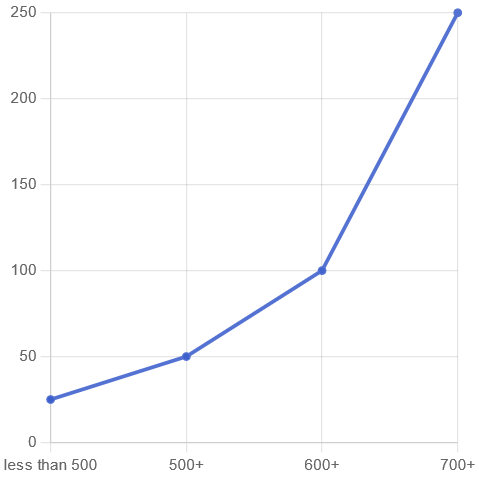
Most small-business financing includes a personal guaranty, so your personal score matters even when the loan is to the business.
- 500+: revenue-based working capital
- 600+: equipment up to about $50K, non-bank loans
- 650+: equipment up to $150K on the application
- 680+: bank loans; 725+ with 5 years for $250K app-only
Turned down before? Start here
What to do if your bank said no.
How we match you with the right lender.
Other things that can move an approval up or down
Before you apply
- Keep 3 to 4 months of clean bank statements with no overdrafts
- Check your personal credit and dispute errors first
- Pay down card balances below 30% of the limit
- Have a vendor quote ready for equipment requests
- Apply for what you need now, not the maximum
- Apply once, through one broker, instead of bank to bank
Straight talk
- “Checking will hurt my credit.” We pre-qualify with a soft inquiry. A hard pull only happens once you're approved and moving forward.
- “My bank said no, so everyone will.” Banks turn down most small-business requests. Non-bank lenders use different rules.
- “Bad credit means no options.” Revenue-based programs look at deposits first, though they cost more.
Documents by request size
| Request | What you usually need |
|---|---|
| Up to $150K | One-page application, 3–4 months of bank statements, vendor quote (equipment) |
| $150K to $250K | Above, plus the last 2 years of business tax returns or financials (application-only up to $250K with 725+ credit and 5+ years) |
| Over $250K | Full financial package: 2–3 years of business and personal tax returns, year-to-date P&L and balance sheet, debt schedule |
| Working capital | Application, 3–4 months of bank statements, ID, proof of ownership |
Approval indicator questions
Does the approval indicator check my credit?
No. It runs in your browser, nothing is saved or sent, and there is no credit inquiry. When you apply, we pre-qualify with a soft inquiry that doesn't affect your score.
Is the indicator an approval?
No. It shows which programs typically fit businesses with your numbers. Your real approval depends on a full review of your application, bank statements and credit.
What credit score do I need for business financing?
It depends on the program. Revenue-based working capital often starts around 500, equipment financing and non-bank term loans around 600, and bank loans usually 680 or higher.
Can a startup get approved?
Yes, mostly for equipment financing. New businesses are considered with strong personal credit, usually with a down payment. Working capital programs typically need at least 6 months of history.
How much can I get on the application alone?
For equipment, up to $250,000 on a one-page application, depending on credit and time in business. Larger requests need financial statements and can go up to $5,000,000.
How fast will I know?
Most applicants hear back within 24 hours. Working capital can fund in 24 to 48 hours, and equipment usually funds 1 to 5 days after signing.
Get your actual approval, not an estimate
One application is sent to the lenders that fit your profile. Soft pull to pre-qualify, no obligation.
Liberty Capital Group, Inc. NMLS #2009539. California loans made or arranged under California Financing Law license #60-DBO49692. The approval indicator is for general information only and is not an offer or commitment to lend.